Buyers Costs
What Should A Buyer Know
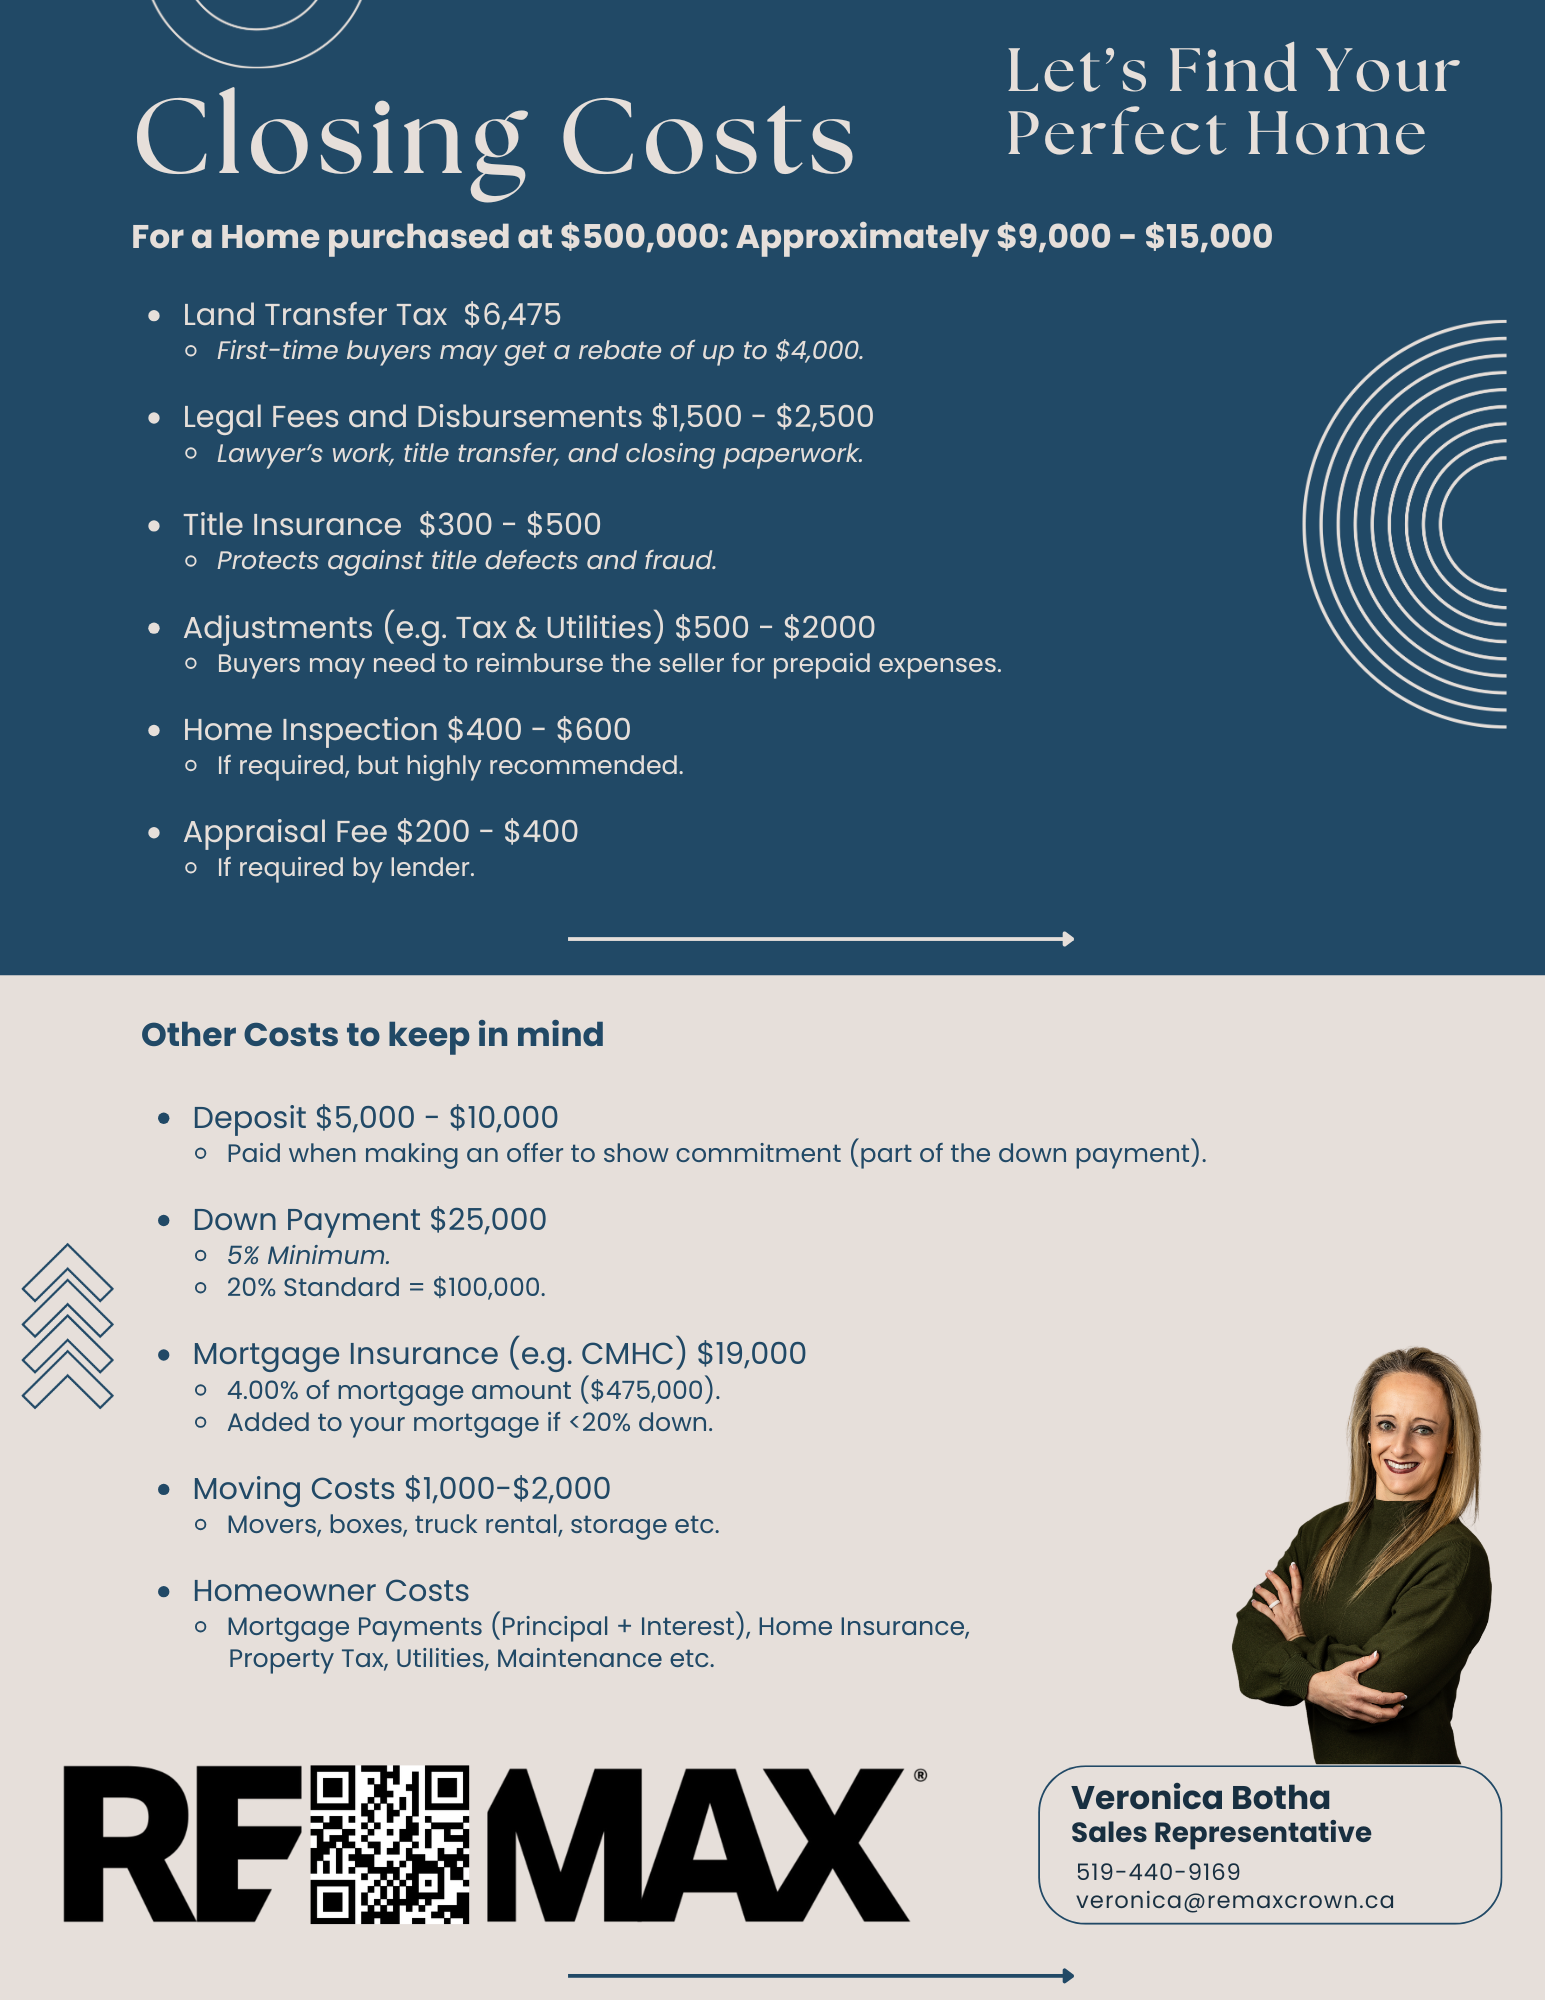
Closing costs are the various fees and expenses that homebuyers must pay to finalize the purchase of a property. In Ontario, it's advisable for buyers to budget between 1.5% and 4% of the property's purchase price to cover these costs. These costs are in addition to the down payment.
Early Preparation: Understand and budget for closing costs early in the home-buying process to avoid unexpected financial strain.
Professional Consultation: Use this as a guideline, then speak with your lawyer who will provide a more realistic estimate for your situation.
First-Time Buyer Incentives: Investigate eligibility for programs and rebates, like the LTT rebate, to reduce overall expenses.
Fees
APPRAISAL FEE
Generally required with new homes, an appraisal provides the lender with a professional opinion of the market value of the property. This cost is normal the responsibility of the homeowner and it ca n cost between $100-$300.
HOME INSPECTION FEE
Generally required with resale homes, a professional inspection of the home can cost anywhere from $300-$400 and is well worth the investment. When hiring a home inspector make sure the inspector has liability insurance just in case they overlook something.
FIRE INSURANCE
Mortgage lenders require a certificate of fire insurance to be in place from the time you take possession of the home. The amount required is generally the amount of the mortgage or the replacement cost of the home. This cost can vary depending upon the property size, amount of coverage, the insurance company and the municipality. The cost can be anywhere from $200-$600 annually for most properties.
ADJUSTMENTS
Buyers may need to reimburse the seller for prepaid expenses like property taxes or utility bills, calculated from the closing date onward.
LAND SURVEY FEE OR TITLE INSURANCE FEE
A recent survey of the property is usually required by lenders. IF one is not available, the cost can range between $600-$900 for a new survey. In lieu of the survey, most lenders today will accept title insurance which can cost considerably less.
LEGAL COSTS AND DISBURSEMENTS
Lawyers and notaries charge fees for their services involved in drafting the title deed, preparing the mortgage, and conducting the various searches. Disbursements are out-of-pocket expenses incurred during the process such as registrations, searches and supplies.
LAND TRANSFER TAX
Most provinces charge a land transfer tax payable by the purchaser. Land transfer tax is based on the purchase price, and can be up to 2.5%. First time home buyers purchasing a new or resale home may be entitled to a refund of the land transfer tax.
PROVINCIAL SALES TAX ON MORTGAGE INSURANCE
If your mortgage is insured (CMHC or Genworth Financial) you will be required to pay the applicable taxes on the insurance premium on closing. While the insurance premium can be added to the mortgage amount, the tax must be paid at closing.
New Home Owner Additional Fees
HST
HST is payable on the purchase of newly constructed homes only. If you are purchasing a new home, make sure you know who pays this, you or the builder. On the offer, the purchase price will say “Plus HST” or HST included” and will stipulate which party is entitled to any HST rebates. Many builders include this cost in the purchase price so the buyer does not have to be concerned with paying it as an additional cost at closing. Buyers should be careful when purchasing vacant land as newly severed property may be subject to HST.
NEW HOME WARRANTY
In most provinces new homes are covered by a new home warranty program. The cost to the purchaser for this warranty is approximately $600 and should the builder default or fail to build to an agreed upon standard, the fund will finish or repair the deficiencies to a maximum amount. For more information on Ontario new home warranty, visit http://www.tarion.com.
What is CMHC?
The Canada Mortgage and Housing Corporation (CMHC) is a government-owned corporation that provides mortgage loan insurance, housing research, and affordable housing initiatives in Canada.
Key Points About CMHC:
Mortgage Loan Insurance: CMHC offers insurance to lenders for high-ratio mortgages (where the down payment is less than 20%), making it easier for buyers to qualify for a home loan.
Premium Costs: The insurance premium is added to the mortgage and varies based on the down payment percentage.
First-Time Homebuyer Programs: CMHC provides incentives, such as the First-Time Home Buyer Incentive, to help with affordability.
Housing Market Research: It conducts studies on the real estate market, rental trends, and housing affordability.
Approximate premiums:
5% down payment: 4.00% of mortgage amount
10% down payment: 3.10% of mortgage amount
15% down payment: 2.80% of mortgage amount
Closing Costs